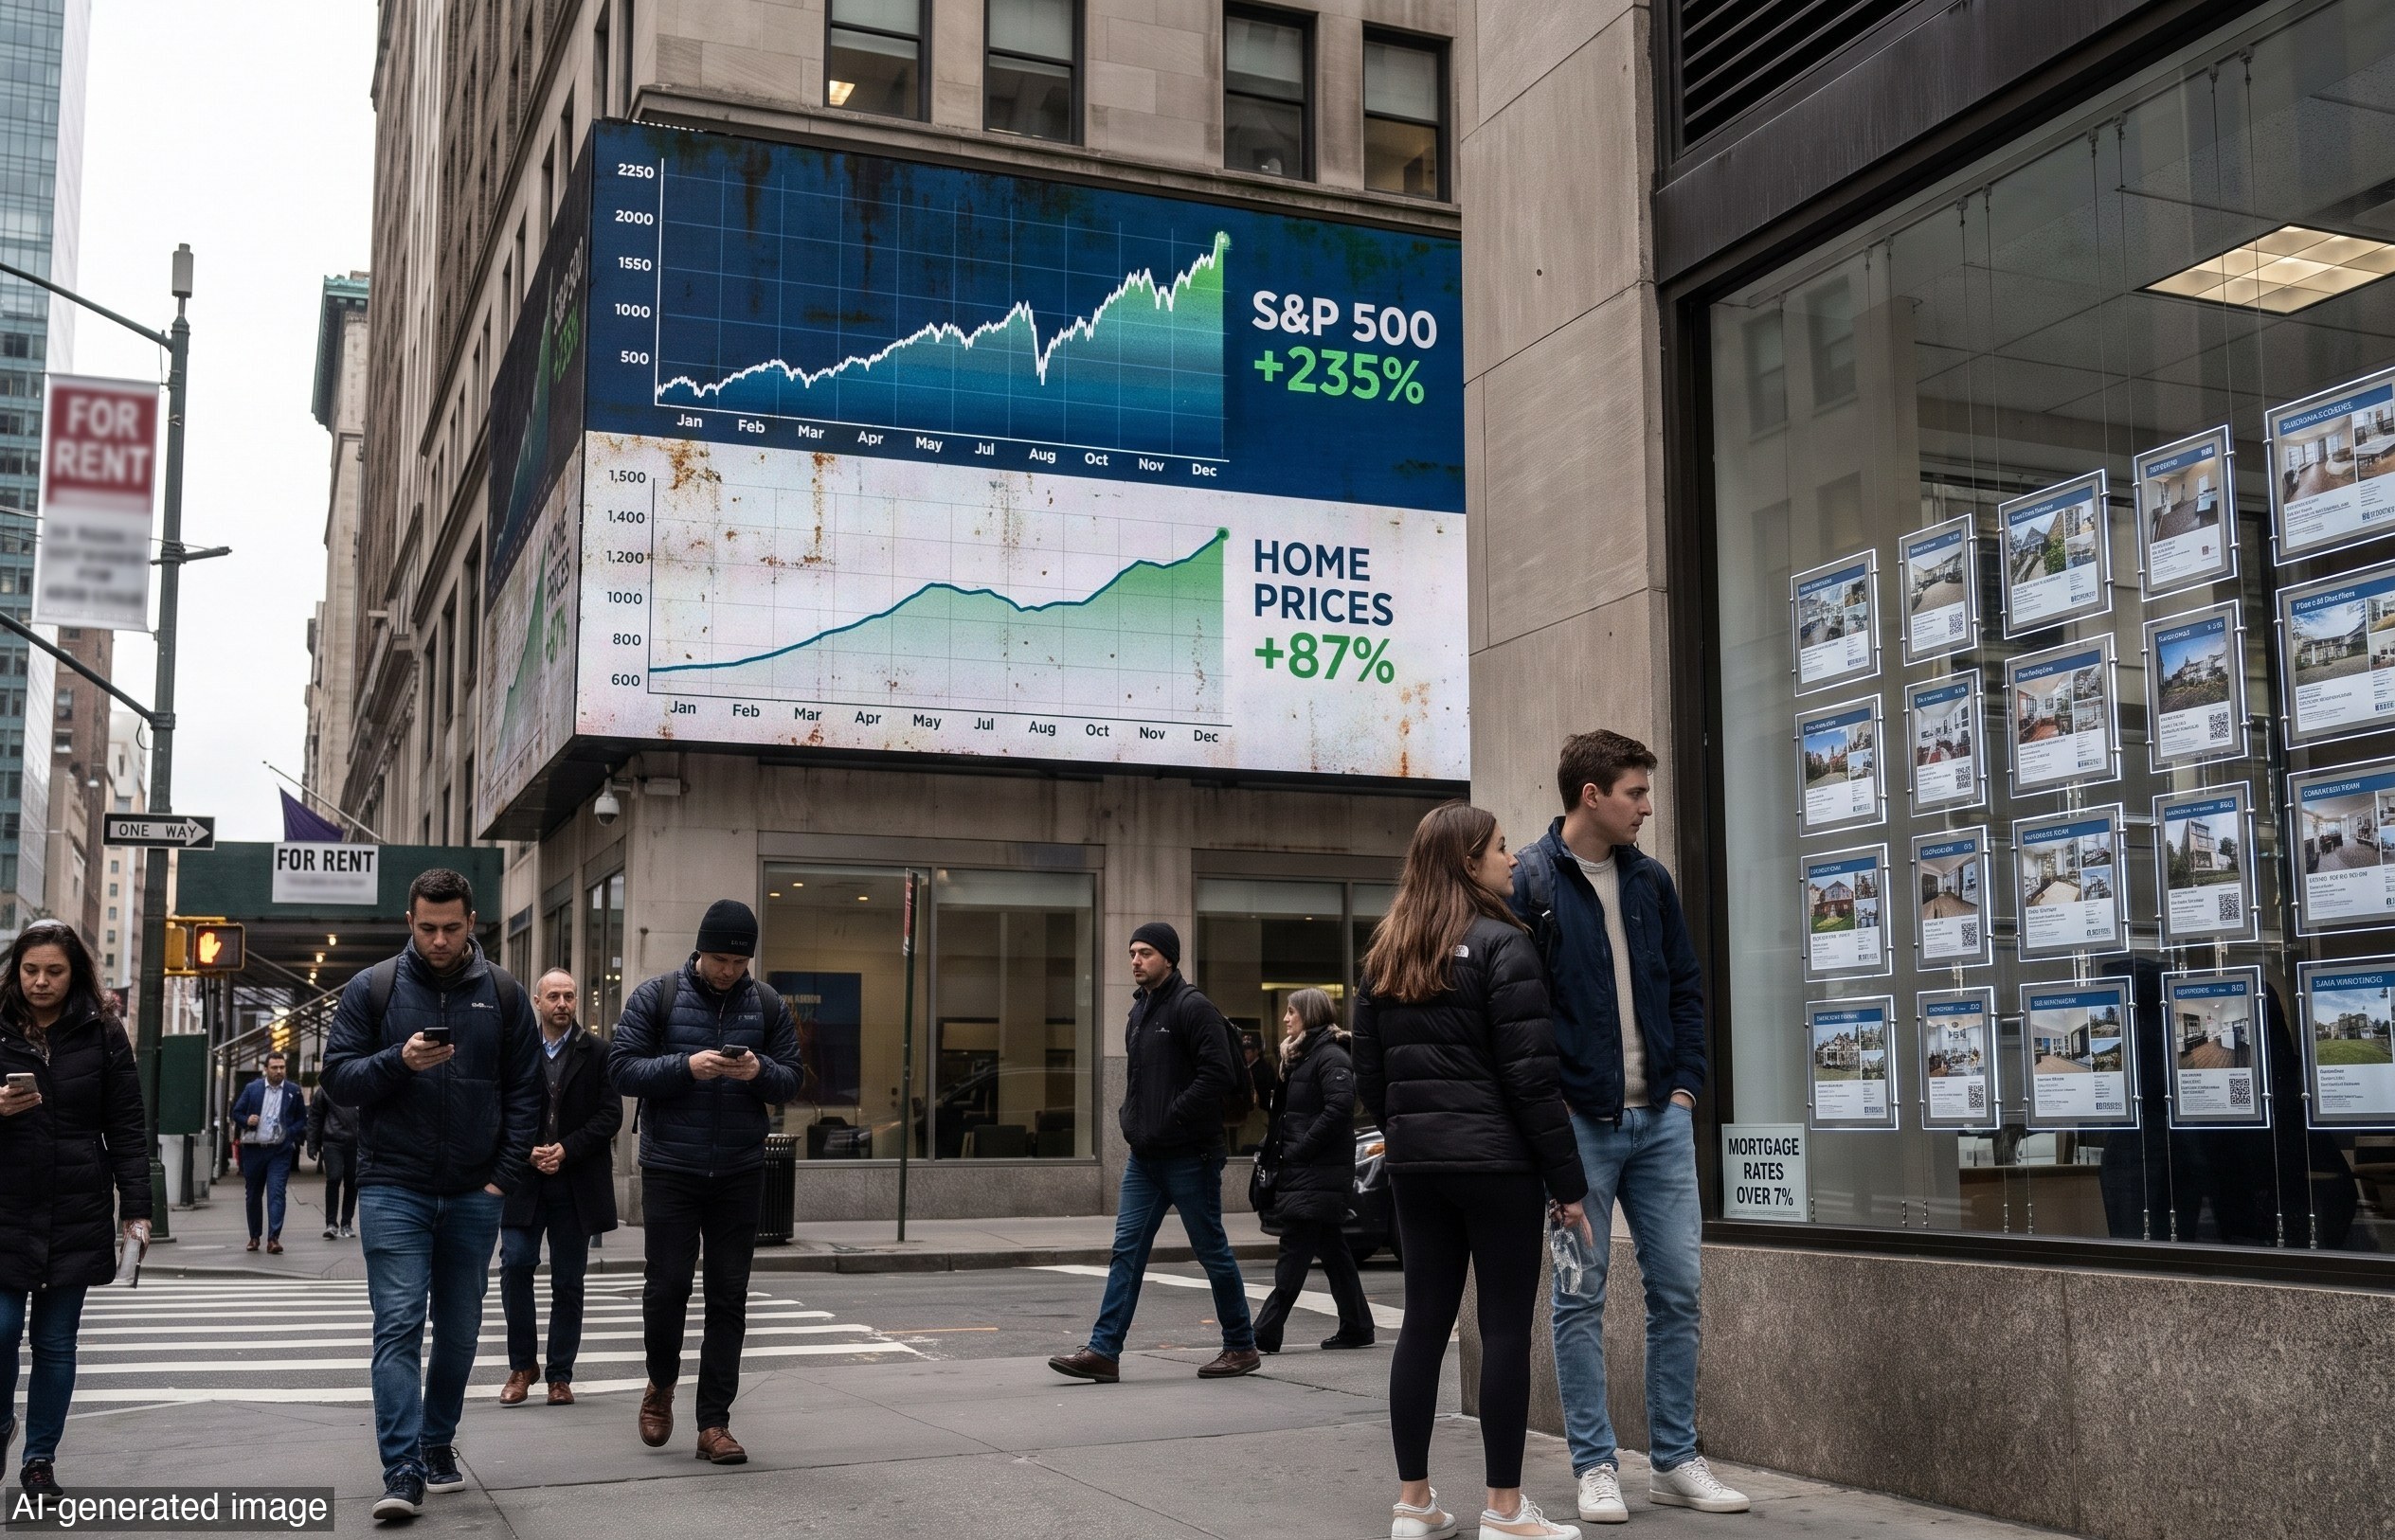
The numbers come first. From December 2015 through December 2025, the Case-Shiller Index of home prices rose 87%, while the S&P 500 soared 235%, not including dividends. In 2026, home prices are up 1.5% nationwide, while the S&P 500 is up 13%.
That gap is widening as the average 30-year fixed mortgage rate moves back above 7%. Fortune reported that the housing market has been largely frozen since the COVID-era boom ended in 2022, when the Federal Reserve began an aggressive rate-hiking campaign to rein in inflation. The same rate pressure that has pinned housing is landing in a stock market boosted by the AI boom and double-digit annual gains.
Younger Americans are responding with a simple calculation. Many are choosing to rent and investing in stocks to build wealth rather than saving for a down payment on a home they may never be able to afford. For them, the market has already voted: capital has found a better return in equities than in shelter.
Ray Fisman, an economist at Boston University, and Michael Luca, an economist at Carnegie Mellon University, argued in a Wall Street Journal op-ed that the rent-versus-buy decision involves real trade-offs that are often overlooked. They wrote that buying a home bundles two different decisions: where to live, and how to invest a large chunk of life savings.
They also noted that the comparison is not perfectly apples to apples. A home provides a place to live, and the U.S. tax code has benefits for homeownership. But the economists said the returns to buying can still be 'meh' even when home prices post robust gains.
Their warning matters because leverage cuts both ways. A homeowner can magnify gains by borrowing most of the purchase price, but declines also hit hard because a home is a 'single, illiquid, undiversified asset.' In their example, a 20% down payment on a house that rises 10% would translate into a 50% return on initial equity. The same structure can work in reverse when prices fall.
The housing side is showing some signs of strain. Redfin said sellers gave concessions in 44.7% of home sales last month, up 2.1 percentage points from a year ago and the highest share for the month of August since at least 2020. Those concessions can include mortgage rate buy-downs, repairs, appliances, and even larger giveaways to close a deal.
Capital rewards clear rules, and right now those rules favor liquidity, diversification, and flexibility. The taxpayer may still subsidize homeownership through the tax code, but the return profile is no longer a given. For many households, especially younger ones, the choice is shifting from ownership at any cost to market exposure with fewer strings attached.
That does not make housing irrelevant. It means the old assumption that a home is always the safest path to wealth is under pressure. When borrowing costs rise and stocks keep climbing, free enterprise sends a blunt message: the best-performing asset is the one the market can price quickly, not the one that takes years to buy and even longer to sell.


