Oil has climbed back above $100 a barrel, but economists quoted by Fortune say that round number is not the main threat to the U.S. economy.
Brent crude rose as high as nearly $110 a barrel on Monday, up 4%, its highest price since May, before easing to around $107 on Tuesday. The move revived fears about inflation and borrowing costs. But the comparison that matters more is what Americans actually pay at the pump and in the supply chain.
Back in 1980, Americans spent about 6% of their income on gas, according to JPMorgan’s analysis. Today, that share is about 2.5%. That means the headline price of crude does not land on households the same way it once did.
What does matter, economists said, is the shortage-driven jump in refined fuels such as gasoline and diesel. Those prices hit consumers directly and then spread through the wider economy. If gas stays high, households cut spending. If diesel stays high, businesses pay more to ship goods, run factories, and operate farm equipment.
Michael Pearce, chief U.S. economist at Oxford Economics, said the U.S. now acts differently because it is a net energy exporter. Higher oil prices are bad news for households, but good news for energy producers, he said. Pearce also said there is not a 'tipping point' for crude prices that automatically sends the economy into recession.
Patrick De Haan, head of Petroleum Analysis at GasBuddy, said $100 oil today does not carry the same weight it did decades ago. He said oil may need to reach closer to $200 to have a similar effect on the economy now.
The bigger problem is refinery capacity. Pearce said the war has put pressure on gasoline and diesel, while refinery shortages have pushed those prices up more than oil alone would suggest. In plain terms, crude is the input; refined fuel is the bill that consumers and businesses must actually pay.
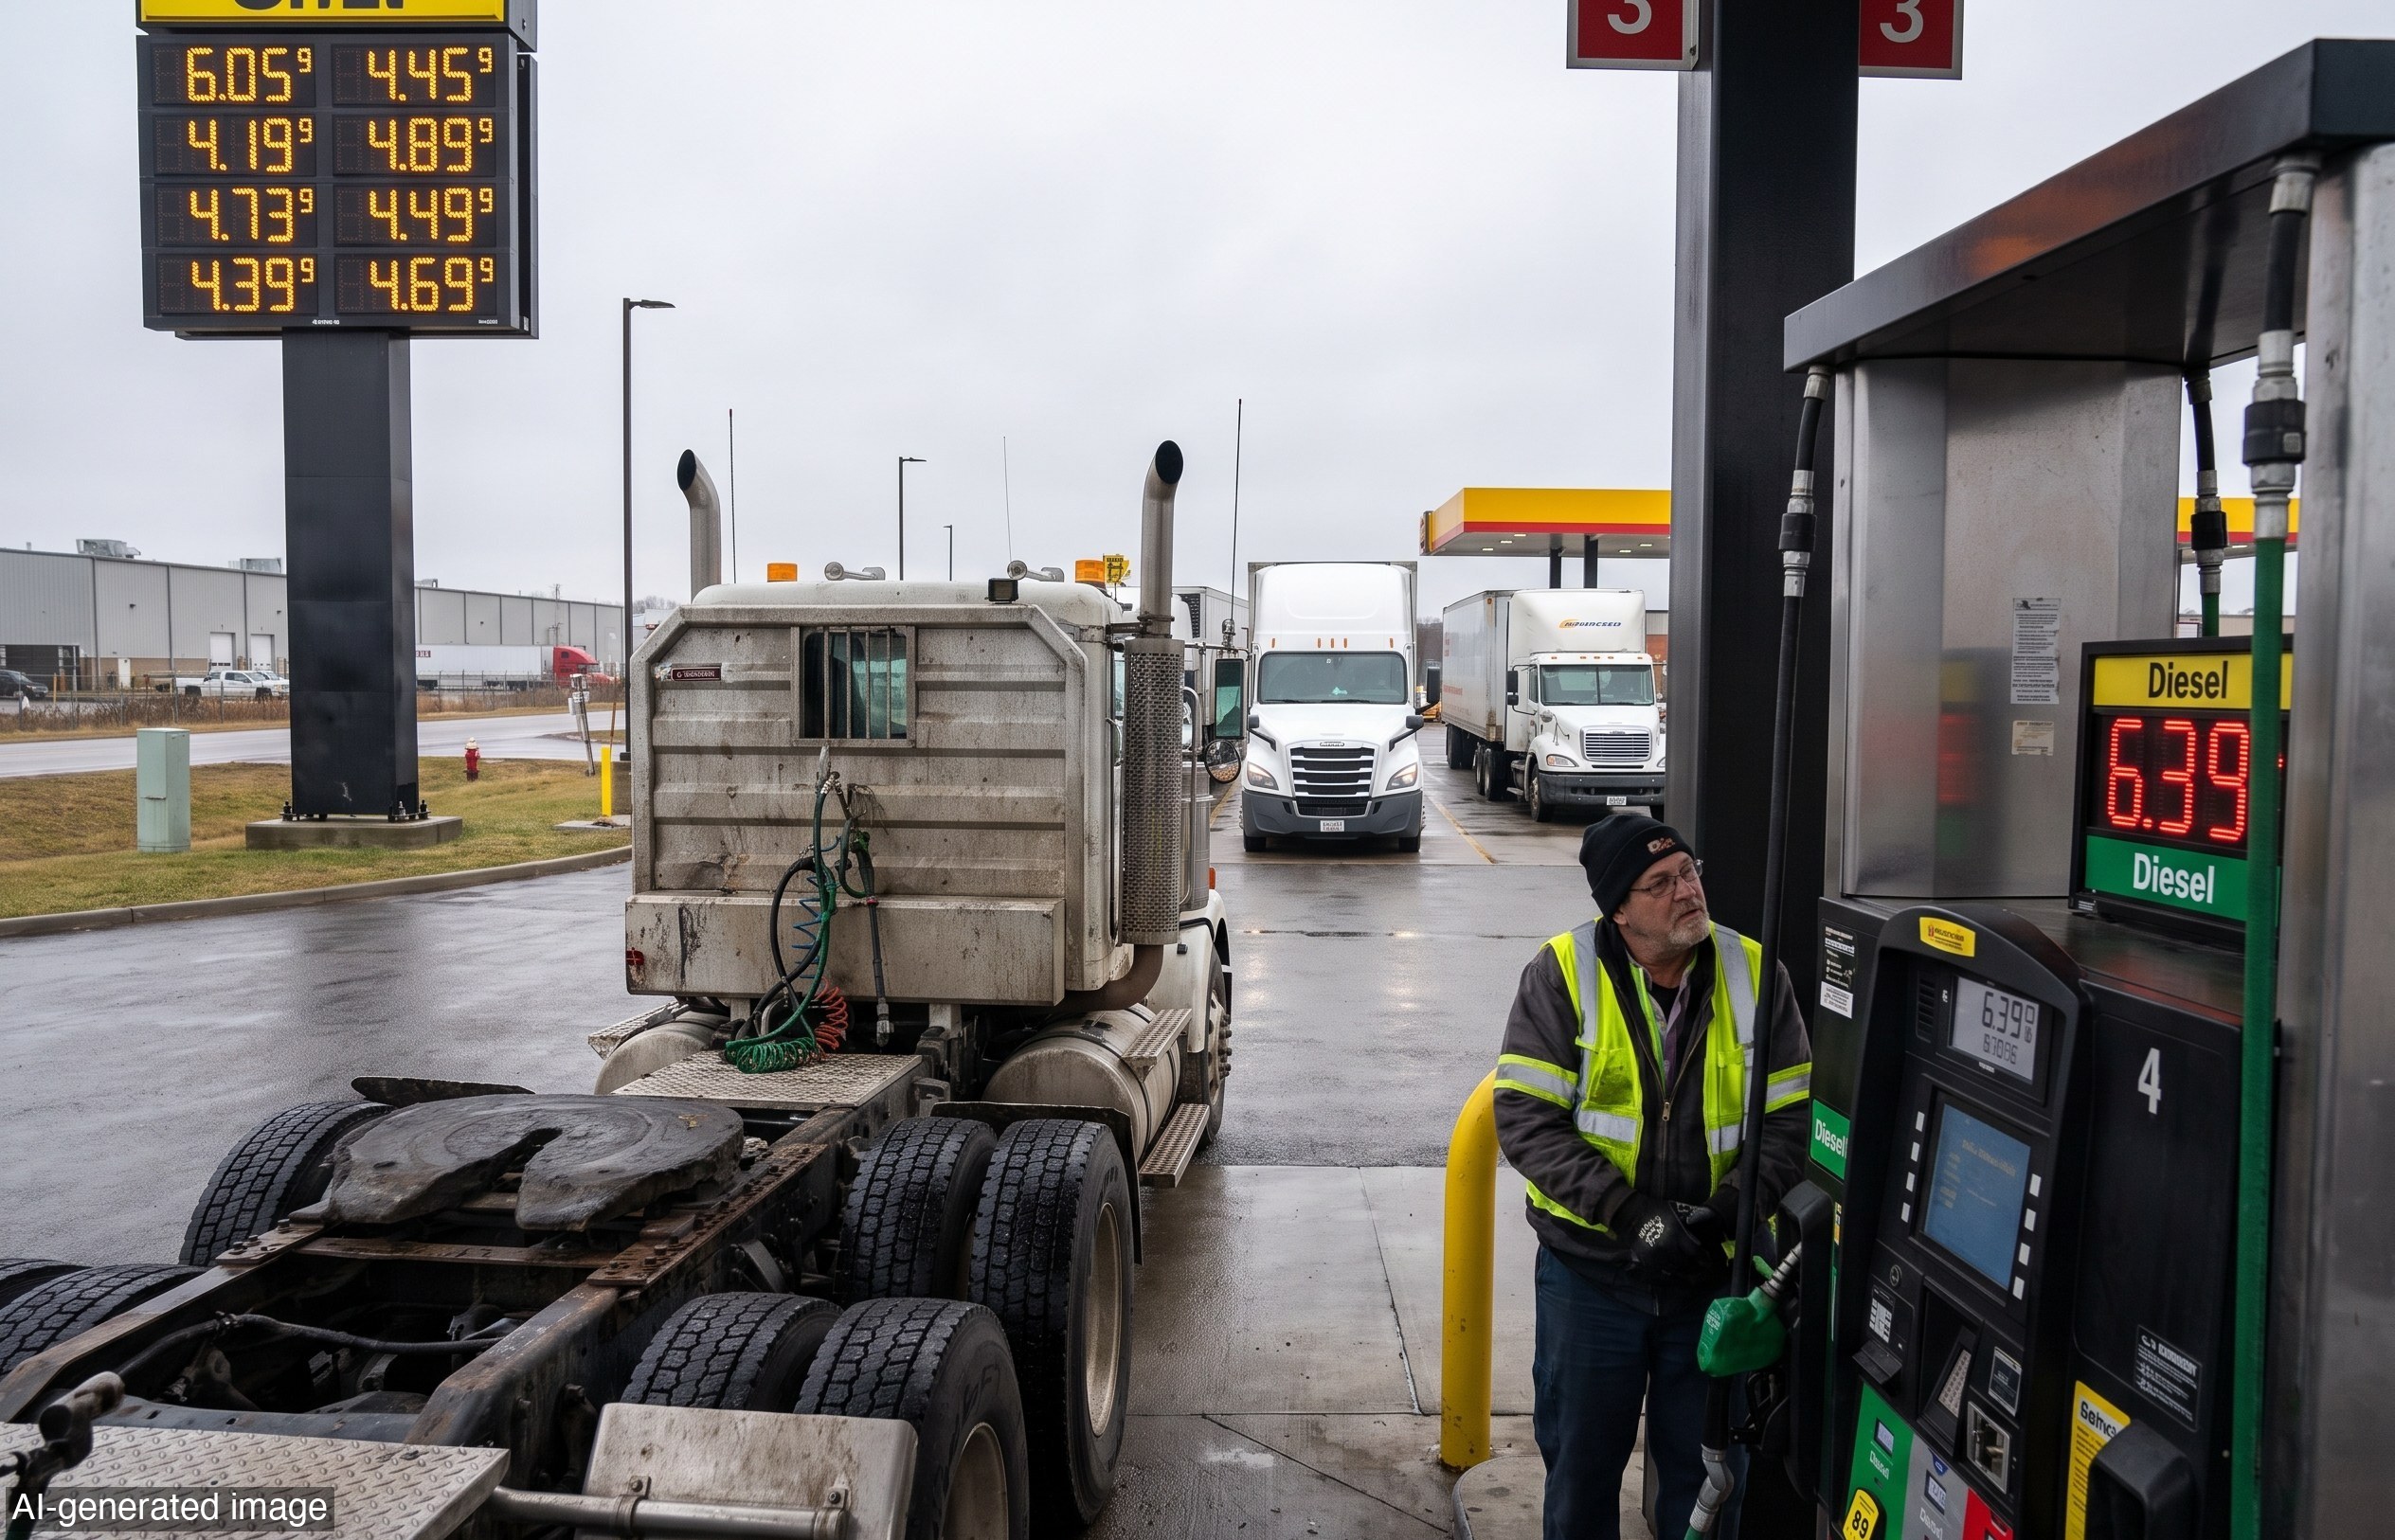
The national average for regular gasoline was trending toward $4.43 a gallon Thursday, up from $3.20 a year earlier, according to AAA. Diesel reached a record of $6.39 a gallon, compared with $3.70 a year earlier.
Oxford Economics estimates that if current prices persist, they could shave a few tenths of a percentage point from consumer-spending growth next year. Pearce said oil closer to $140 would start causing more serious problems, though the damage would be smaller in the U.S. than in countries where energy takes up more of household budgets.
Lower-income Americans are already exposed to the squeeze. JPMorgan said they spend more of their income on essentials beyond gas, leaving less room to absorb higher prices. De Haan said diesel’s indirect costs have not become 'insurmountable' yet, but consumers could face more pressure around or shortly after the holidays if prices stay elevated.
The lesson is simple: markets do not care about political slogans, only incentives and costs. A crude benchmark may make headlines, but it is gasoline, diesel, and the taxpayer-adjacent drag on private spending that determine whether growth holds up or gets pinched. Capital rewards clear rules, not empty reassurance.


